Updated 24 April 2026
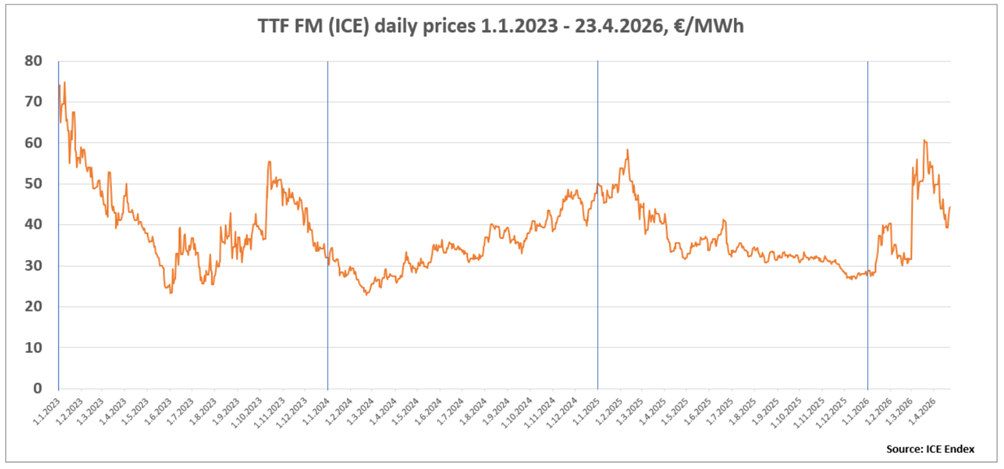
Following the US and Israeli strikes on Iran, daily TTF gas prices rose rapidly from around €30/MWh to €50/MWh. From the beginning of March, daily prices ranged between €47 and €61/MWh until 8 April, when the ceasefire brought them down to €45/MWh. Since then, daily prices have ranged between €39 and €46/MWh.
Uncertainty remains in the European gas market, making short-term price developments difficult to assess. Most LNG deliveries to Europe come from the United States and Norway, and the situation in the Strait of Hormuz has had no direct impact on supplies. However, growing interest among Asian buyers in LNG cargoes destined for Europe has been reflected in European exchange prices.
An inverted summer–winter price spread is slowing storage replenishment
Low European gas storage levels are also maintaining pressure on the market. Storage is around 31% full, well below the five-year average of 43%. However, warm weather in Europe meant that storage levels barely fell further in March, and they have now started to rise.
Storage replenishment is currently being held back by an inverted summer–winter price spread. Because of the crisis in Iran, forward prices for next winter are unusually below current spot prices, making gas storage uneconomic. Winter prices would need to be at least a few euros higher than spot prices to cover storage costs. At present, next winter’s forward prices are €1–2/MWh below spot prices.
Prices may continue to fluctuate over the coming months
The near-term direction of prices remains difficult to predict. Gas prices have stayed relatively moderate considering the scale of the crisis (see the price chart below). If the situation in the Persian Gulf continues to ease and LNG shipments return to normal, prices could quickly fall below €35/MWh.
If uncertainty persists, daily price volatility on European gas exchanges is likely to remain high, and the risk of prices rising above €50/MWh again remains.
The two-week ceasefire that began on 8 April has been extended, but the negotiating situation between the United States and Iran still looks challenging.
Pekka Karinen
Director, Gas Sales
Updated 13 March 2026
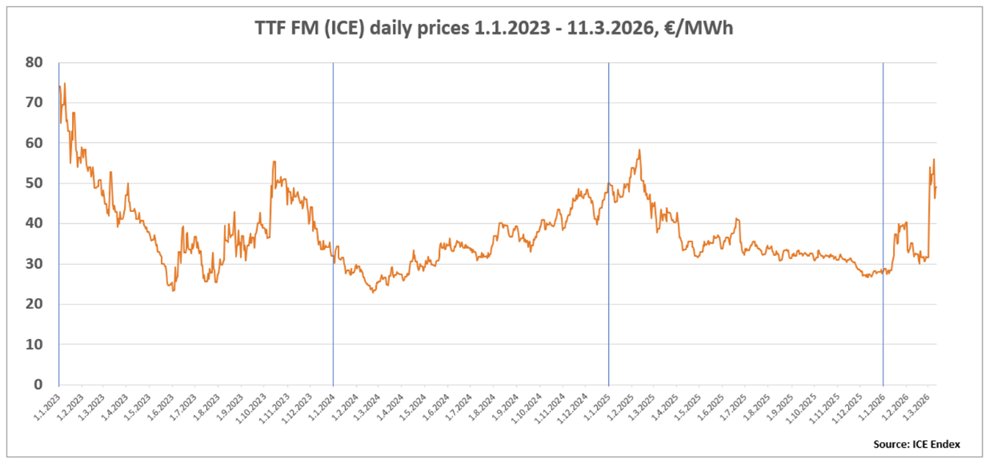
Daily gas exchange price volatility has increased significantly since the end of February. The escalation of the dispute between the United States and Iran into war has increased market uncertainty, compounded by concerns about energy shipments passing through the Strait of Hormuz.
Daily prices on the Dutch TTF gas exchange rose from around €32/MWh to approximately €55/MWh at the beginning of March. Since then, they have ranged between €46 and €56/MWh and are now around €50/MWh.
Most of Europe’s LNG comes from the US and Norway
Liquefied natural gas (LNG) from the Persian Gulf is destined for Asian markets. Europe’s LNG comes mainly from the United States and Norway, so problems in the Strait of Hormuz have no direct short-term impact on European deliveries. If the situation in the Strait persists, Asian gas buyers will begin competing for LNG cargoes destined for Europe, pushing up European exchange prices.
The situation is further weakened by low levels in Europe’s underground gas storage facilities. Storage is currently around 29% full, compared with a five-year average of 43% at this time of year. A year ago, it was around 36% full.
Warm weather in Europe means that storage levels have not fallen further in March. Gas demand will also decline further as spring progresses.
Price volatility may continue over the coming months
At the time of writing (12 March), the market is pricing gas for the second quarter of 2026 at around €50/MWh and for the third and fourth quarters at approximately €48–49/MWh.
Over the longer term, futures markets are pricing gas at lower levels. The calendar-year price is around €37/MWh for 2027, €26/MWh for 2028 and €23/MWh for 2029.
The direction of gas prices is currently very difficult to assess. If oil and LNG tankers start passing through the Strait of Hormuz, gas prices could fall quickly. If the situation persists, daily price volatility on European gas exchanges is likely to remain high, with a risk of higher near-term gas prices.
Updated 5 February 2026
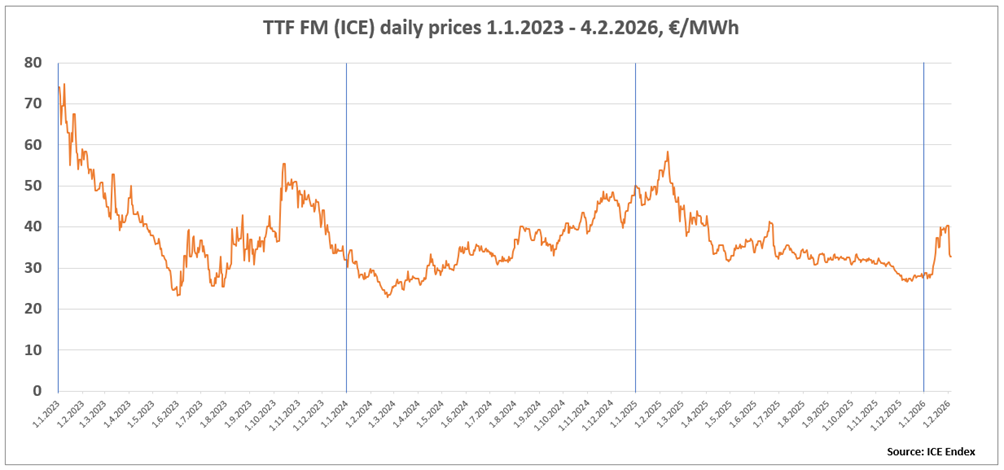
Daily prices on European gas exchanges rose in January as the weather turned colder. Daily TTF prices on the Dutch ICE exchange rose from a low €27–28/MWh at the start of the year to around €38–39/MWh in the second half of January.
The rapid increase was reinforced by lower-than-usual European gas storage levels and exceptionally cold weather in the United States at the same time, which diverted gas intended for LNG production and export to the pipeline gas market.
Thanks to low prices in the first half of January, however, February’s ICE TTF Front Month price—the monthly price commonly used in gas billing—remained relatively reasonable at €33.64/MWh.
Milder weather forecasts pushed prices down in early February
Long-range European weather forecasts became milder in the first week of February, bringing daily March Front Month prices down to €33/MWh within a couple of days.
Weather forecasting has proved unusually difficult this winter because of a weak polar vortex. The cold air mass above the North Pole has not remained in place, but has periodically moved further south than usual across Europe and North America, causing sudden cold spells.
Forward prices point to moderate price developments
Forward prices for spring and the rest of the year are currently around €31–32/MWh, meaning their increase has been more moderate than that of daily prices.
January’s price fluctuations have also had little effect on longer-term forward prices. These indicate around €26/MWh for 2027, €23/MWh for 2028 and below €22/MWh for 2029. The latter figures are already close to the long-term average gas price before the energy crisis.
European gas storage is currently around 41% full, compared with a five-year average of 58% at this stage of winter. Low European storage levels will keep the market tight for the rest of winter and into spring. This increases the risk of price rises if European weather forecasts turn colder than usual or other negative surprises occur in the market.
Price developments resemble last winter
Current gas price developments resemble last winter in many respects. At that time, cold weather and low storage levels drove daily prices up from the beginning of January to nearly €60/MWh in mid-February, after which they quickly fell first to around €40/MWh and then to €35/MWh.
So far this year, price movements have been considerably more moderate, although storage levels are lower than last winter.
In summer 2025, daily gas prices briefly rose to around €40/MWh following the conflict between Israel and Iran, before falling back to €34–35/MWh as the situation eased. During autumn, prices remained stable at €32–35/MWh and fell towards €27–28/MWh by the end of the year.
Price stability was supported by milder-than-usual European weather, strong Norwegian pipeline gas flows and good global LNG availability. Weak industrial gas consumption in the EU due to economic conditions, together with increased wind and solar generation, also weighed on prices.
The LNG-based market has changed price dynamics
European gas market dynamics changed when Russian pipeline gas was replaced by LNG from the global market during 2022–2023. Before this, gas in Europe was generally significantly more expensive in winter than in summer because of bottlenecks in transmission connections from Russia.
In an LNG-based market, gas prices are more widely influenced by the global balance of supply and demand, as well as geopolitical risks and events. At the same time, lower European gas consumption has reduced seasonal fluctuations.
EU finally decides on a ban on Russian gas imports
During 2025, the EU prepared a ban on Russian LNG and pipeline gas imports, which progressed despite opposition from some Member States. The ban received final approval on 26 January 2026 with support from a majority of Member States.
The import ban will not take effect immediately: existing contracts were granted transition periods. Short-term contracts concluded before 17 June 2025 may continue until 25 April 2026 for LNG and until 17 June 2026 for pipeline gas. Long-term LNG contracts may remain in force until the end of 2026, and long-term pipeline gas contracts until 30 September 2027.
Pipeline gas flows from Russia to Europe have been very limited since summer 2022, consisting of relatively small volumes via Turkey. Russian LNG has continued to be imported into Belgium, France and Spain.
Despite the transition periods, the ban can be regarded as a significant EU achievement.
Gas has once again secured Finland’s energy supply
In the Finnish market area, daily gas prices have risen above those in the Baltic countries because of cold weather, high electricity prices and the limited capacity of the Balticconnector pipeline linking Finland and Estonia.
Despite exceptionally high gas consumption, Finland’s gas transmission network has remained stable. Daily consumption peaks have reached 120 GWh, and gas has once again demonstrated its central role in securing Finland’s energy supply.
Pekka Karinen
Director, Gas Sales
Updated 18 September 2025
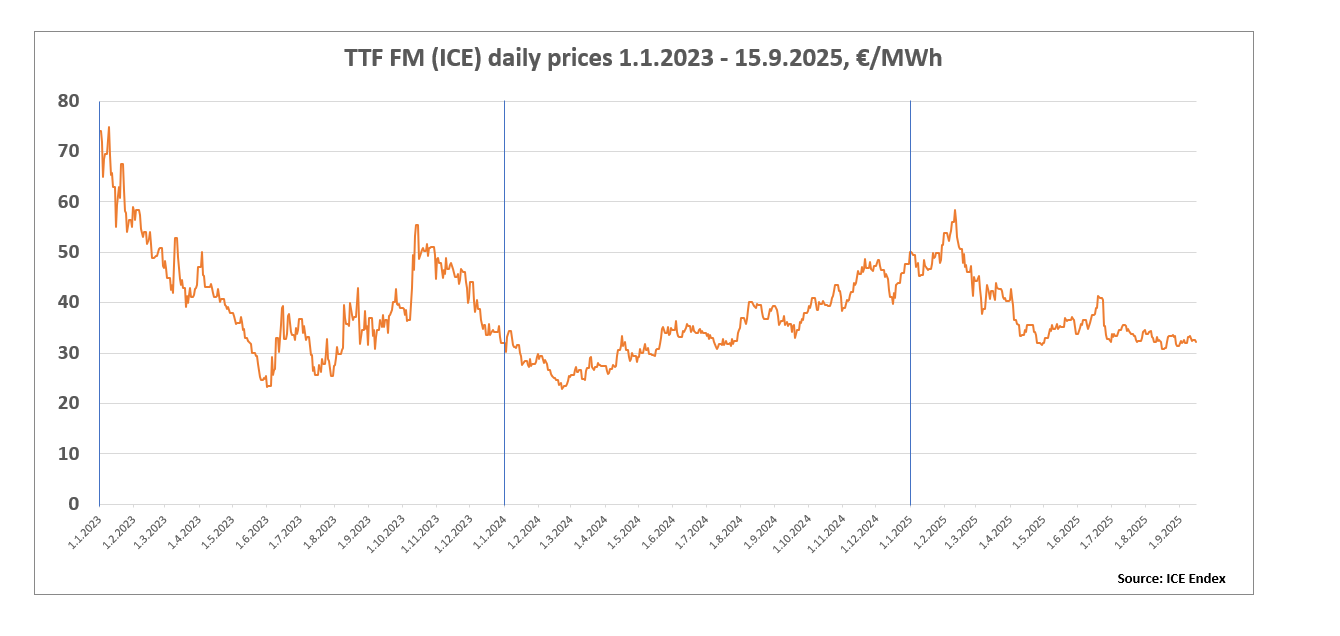
European gas exchange prices have remained fairly stable through late summer and early autumn. Daily TTF Front Month prices, which also underpin gas pricing in Finland, have ranged between €31 and €35/MWh since late June. September’s price level is around €33/MWh.
Markets expect prices to remain moderate
At the time of writing, TTF forward prices for the rest of 2025 are around €33–34/MWh. Prices of approximately €34/MWh are forecast for the first quarter of 2026 and €31–32/MWh for the remainder of 2026. The current forecast is also around €30/MWh for 2027 and €27/MWh for 2028.
Gas storage levels are lower than last year
Europe’s underground gas storage facilities are currently 80% full. The five-year average at this time of year is 87%, and the figure a year ago was 93%.
On 25 June, the European Parliament and Member States decided to retain the 90% gas storage filling target. However, Member States may deviate by 10 percentage points in difficult market conditions. The target can be met flexibly between 1 October and 1 December, and the filling obligation has been extended until the end of 2027. The market is confident that storage will reach the required level by early December.
Updated 25 June 2025
Daily TTF Front Month gas exchange prices have ranged between €32 and €43/MWh since March. The current daily quotation for July TTF FM is around €36/MWh. The ceasefire between Israel and Iran that began on 24 June 2025 reduced the price by around €5/MWh.
The June TTF FM (ICE) monthly price was €35.19/MWh, and the July monthly price, which is almost fully determined, currently stands at €37.12/MWh (25 June 2025).
Markets expect prices to fall over the long term
TTF forward prices for the remainder of 2025 are around €36–38/MWh. Prices are approximately €37/MWh for the first quarter of 2026 and €34/MWh for the rest of the year.
A price level of €30/MWh is forecast for 2027 and around €26/MWh for 2028.
Geopolitics have driven gas price fluctuations
The conflict between Israel and Iran has increased geopolitical risk and caused fluctuations in daily European gas exchange prices. Prices peaked at around €42/MWh before falling to €36/MWh following the ceasefire that began on Tuesday 24 June 2025. The gas market has been monitoring the conflict and its impact on gas prices.
The conflict does not affect gas production, but a potential closure of the Strait of Hormuz would prevent LNG deliveries from the Persian Gulf, mainly to Asia. Reduced LNG availability in Asia would indirectly raise prices for LNG cargoes heading to Europe from elsewhere, as Asian countries began competing for them. The Strait of Hormuz has never been closed, and market participants have regarded closure as unlikely.
There is still plenty of time to replenish gas storage
At the time of publication, Europe’s underground gas storage facilities are 56% full, compared with a five-year average of 66% and 75% at the same time last year. The EU no longer requires storage to be 90% full specifically at the beginning of November: the target can be met flexibly between October and early December. This has significantly eased pressure to refill storage.
Under the updated rules, the 90% target is also no longer absolute. Member States may deviate by 10 percentage points if market conditions are challenging.
Plans to ban Russian gas have become more detailed
The European Commission has published further details of its plan to phase out Russian pipeline gas and LNG entirely by the end of 2027. Spot-traded deliveries are to end by the end of this year, and all deliveries of gas of Russian origin by 1 January 2028. Only very small volumes of Russian pipeline gas now flow to EU countries, and only via Turkey, although LNG has continued to arrive in Belgium, France and Spain.
The ban is intended to be implemented through legislation, requiring approval from the European Parliament and at least 15 Member States representing more than 65% of the EU population. This would prevent individual countries from blocking the ban.
Updated 16 May 2025
Daily gas exchange prices in April and May have fallen considerably from January–February levels. Over the past month, daily TTF Front Month prices have ranged between €31 and €36/MWh, compared with around €50/MWh early in the year.
The realised TTF Front Month monthly price was €41.96/MWh for April and €35.61/MWh for May. Forecasts for the rest of the year range between €35 and €37/MWh.
Gas prices have fallen amid hopes of progress in the Ukraine peace process and fears of a global economic recession due to trade tensions. The EU has also decided to lower its early-November natural gas storage filling target from 90% to 83%.
Underground storage is currently 43% full, compared with a five-year average of 53% at this time of year and 65% a year ago. Substantial LNG arrivals in Europe have allowed storage to fill faster than average.
The European Commission has also recently presented a preliminary plan to ban imports of Russian LNG and pipeline gas by 2027.
Updated 19 March 2025
Daily next-month (Front Month) quotations on Europe’s largest gas exchange, TTF, have ranged between approximately €38 and €60/MWh early this year. The realised TTF FM (ICE) price was €45.07/MWh for January 2025, €48.13/MWh for February and €50.71/MWh for March.
The price outlook for 2025 as of 19 March is as follows: the partially determined April TTF FM price is €41.5/MWh; TTF forwards indicate €41/MWh for May–October and €40/MWh for November–December. For 2026, prices are expected to fall to €35/MWh.
Daily gas exchange prices have been quite volatile in recent months. As expected, the gas transit agreement between Ukraine and Russia expired at the turn of the year. Despite the end of Russian gas flows through Ukraine, supplies have been sufficient in the Hungary–Slovakia–Austria region.
In the first week of January, the daily TTF exchange price fell from €50/MWh to €45/MWh. Prices then rose steadily to almost €60/MWh by mid-February, driven by colder weather and high withdrawals from underground gas storage. Long-range European weather forecasts turned warmer in mid-February, after which prices fell to their current €40–42/MWh level.
Europe’s underground gas storage facilities are currently around 35% full, compared with a five-year average of 48% at this time of year and 59% a year ago.
Key factors in the gas market this winter have been colder-than-usual European weather, low gas storage levels and progress in talks relating to peace negotiations in Ukraine.
Updated 20 December (originally published 25 November 2024)
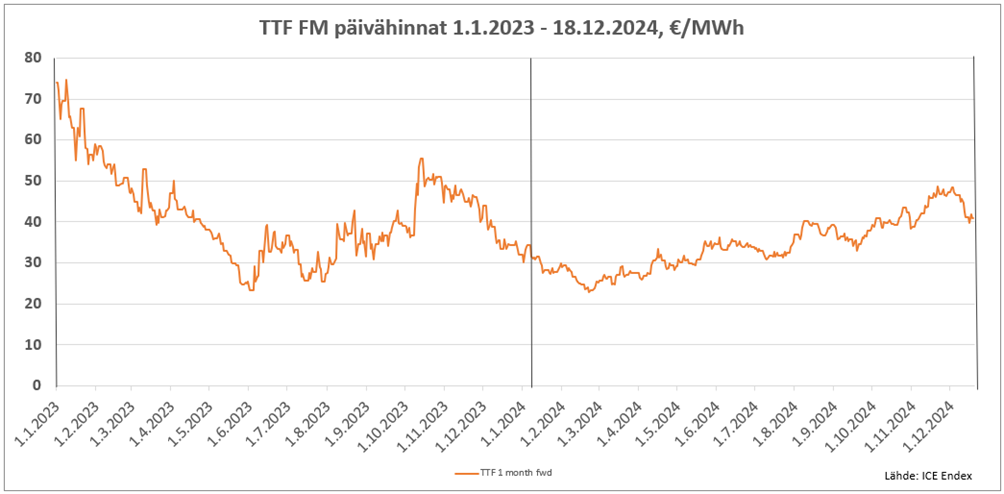
Daily next-month (Front Month) quotations on Europe’s largest gas exchange, TTF, have ranged between €33 and €49/MWh during autumn. The realised monthly reference price (TTFI FM) for exchange-linked gas sales products was €36.24/MWh for October, €40.36/MWh for November and €43.75/MWh for December. The current TTFI FM forecast for January is €44.5/MWh (19 December 2024).
The price outlook for 2025 is also fairly consistent. TTF forwards indicate €43/MWh for January–March and €41–43/MWh for the rest of the year. Prices are expected to fall to €36/MWh in 2026 and further to €30/MWh in 2027.
Daily gas exchange prices have remained fairly stable during autumn despite increased geopolitical risks. Ukraine’s counteroffensive into Russia’s Kursk region, through which gas still flows to Europe via Ukraine, raised daily gas prices by around €5/MWh in early August. Increased tensions and events in the Middle East have also had little significant effect on daily gas prices. The US presidential election result was not reflected in gas prices, but over the longer term Trump’s policies are seen as increasing US gas production and thereby lowering global LNG prices.
According to current information, the gas transit agreement between Ukraine and Russia is due to expire at the turn of the year. Over the past two years, Russian pipeline gas has flowed to Europe only via Ukraine and Turkey, at around 400–500 GWh per day along each route. Expiry would therefore reduce Russian pipeline gas deliveries from around 1,000 GWh to approximately 500 GWh per day. Before Russia’s war of aggression, daily deliveries to Europe through the various pipelines, including Nord Stream and Yamal–Poland, totalled around 4,000 GWh. The market has long known about the agreement’s expiry, and it is not expected to raise gas prices significantly.
Several rumours emerged during autumn suggesting that gas flows to Europe via Ukraine might continue. In recent days, reports have indicated that talks are still being held on transporting Azerbaijani gas through Russia and Ukraine to Slovakia and Hungary. Whether gas will continue to flow to Europe via Ukraine after the turn of the year remains to be seen, although this is unlikely. We would like to reiterate that Auris does not buy or sell Russian gas under any circumstances.
One of the most important factors affecting European gas prices is the level of underground gas storage. Over the past four weeks, colder-than-usual weather in continental Europe reduced storage levels and pushed daily Front Month prices from €42/MWh to nearly €50/MWh. European weather has since warmed, and long-range forecasts indicate warmer-than-usual conditions well into January. More LNG cargoes are also heading to Europe than in recent weeks. Mainly because of these changes, daily Front Month prices and next year’s forward prices have fallen to €40–43/MWh in recent days. Europe’s underground gas storage is around 78% full, close to the five-year average. Storage levels are not expected to fall significantly during the rest of the year, allowing next year to begin with reasonably high stocks.
The coming winter looks positive for Finland’s gas supplies. The Balticconnector pipeline, which links the Finnish gas market to the Baltic countries and was repaired in April, has been operating normally. Its capacity of around 70 GWh per day is sufficient to meet Finland’s gas needs on normal winter days. According to information published by Gasgrid Finland, LNG cargoes will arrive at the Inkoo import terminal during winter. Together, these supplies are sufficient to meet Finland’s needs even on the coldest winter days.
Wishing you a peaceful and enjoyable Christmas!
Pekka Karinen
Director, Gas Sales
Updated 29 May 2024
European gas exchange prices have remained between €23 and €35/MWh since mid-December 2023. The forecast price for June is around €31/MWh, while prices for the rest of the year are expected to range between €36 and €39/MWh.
EU gas storage levels remain high. Storage is currently 67% full, compared with a five-year average of 52%. Asian demand for liquefied natural gas (LNG) has remained low, global LNG availability is good and LNG shipping charter rates are low.
In Finland, the Balticconnector pipeline linking us to Estonia has been repaired and available to the gas market since late April.
Updated 15 February 2024
Gas exchange prices have remained between €27 and €30 since our last update. The realised February Front Month price at the TTF gas hub is around €28/MWh (8 February 2024). Prices for the rest of the year are forecast to range between €28 and €31/MWh.
The same factors as before have continued to keep gas prices moderate. Europe’s underground gas storage levels remain high for the season. Storage is around 67% full, compared with a five-year average of around 52% at this time of year. Weather forecasts have also continued to predict warmer-than-usual conditions in Europe.
In Finland, the Inkoo LNG terminal has operated well and the gas market has remained balanced. Gasgrid Finland still expects the Balticconnector pipeline linking Finland and Estonia to return to service during April 2024.
Updated 19 January 2024
Gas exchange prices have remained between €30 and €35 over the past month. The forecast February Front Month price at the TTF gas hub is around €31/MWh (17 January 2024). Prices for the rest of the year are currently expected to range between €28 and €32/MWh.
Gas prices have continued to be kept moderate by high underground storage levels and forecasts of a warmer-than-usual winter.
In Finland, the Inkoo LNG terminal has operated well and the gas market has remained balanced. Gasgrid Finland still expects the Balticconnector pipeline linking Finland and Estonia to return to service during April 2024.
Updated 21 December 2023
European gas exchange prices have fallen significantly during November and December. The forecast January Front Month price at the TTF gas hub is now around €37/MWh. Next year’s gas prices are currently expected to range between €33 and €38/MWh.
In recent weeks, prices have been pushed down by Europe’s still very high underground gas storage levels and forecasts of a warmer-than-usual winter. At the time of writing, storage is around 88% full, compared with a five-year average of 76% for this time of year.
European gas prices have also been restrained by factors including the significant expansion of LNG import capacity in several European countries since the war in Ukraine began.
Updated 25 October 2023
The European gas market has reacted to world political events in October, but gas prices have nevertheless risen fairly moderately. Daily Front Month prices ranged between €30 and €55/MWh during September and October. The current forecast November Front Month monthly price at the TTF gas hub is around €45/MWh. A price level of around €55/MWh is forecast for both winter and next summer.
The main reason for rising European gas prices is the conflict between Hamas and Israel, which has increased geopolitical risk in energy markets. The threat of strikes at Chevron’s Australian LNG plants throughout autumn has also increased price volatility in Europe. Employers and employees have just reached an agreement, removing the strike threat.
Rising exchange prices have been restrained by Europe’s very high underground gas storage level of around 98%. The relatively high €50–55/MWh forecast for next summer reflects uncertainty over how cold and long the winter will be and how far storage levels will fall. One estimate suggests that storage falling below around 46% would significantly increase Europe’s LNG import needs compared with the past year.
Finland’s gas transmission system operator Gasgrid Finland and Estonia’s Elering detected an unusual pressure drop in the subsea gas pipeline connecting Finland and Estonia on 8 October 2023. The pipeline valves were closed immediately, and no gas is currently being transported between the countries through the pipeline. Investigations revealed damage that will take until at least next April to repair. Auris is following developments in its Balticconnector update.
Despite the pipeline damage, Finland’s gas market remains stable. Gas is arriving through the Inkoo LNG terminal and the smaller terminal in Hamina, among other routes. Inkoo’s capacity is sufficient to secure Finland’s entire gas consumption, including higher winter demand.
Updated 15 September 2023
September has largely continued in the same vein as August in the gas market. The realised September TTF Front Month price was around €35/MWh. A similar price level is forecast for October.
The expected TTF forward price is currently €46/MWh for November and €51/MWh for December.
For next year, prices are forecast at approximately €52–55/MWh.
Updated 22 August 2023
European gas exchange prices have fluctuated somewhat over the summer, but daily prices have nevertheless remained reasonable at around €25–40/MWh.
The current forecast TTF gas exchange price for September is around €34/MWh (21 August). Towards the end of the year, monthly forward prices rise to €40–55/MWh.
For the whole of next year, prices are currently forecast at around €53–56/MWh.
Gas storage is nearly full
Europe’s underground gas storage facilities are currently more than 90% full, which bodes well for the coming autumn and winter. The EU’s target was to reach 90% by early November.
The five-year average filling level at this time of year is around 77%. Last year, storage was 76% full at this point.
Gas price fluctuations remain greater than usual
Front Month gas prices have remained almost unchanged throughout the summer, but prices are still much more volatile than before the war in Ukraine. This means that market events and developments in gas production move prices more readily than we have historically been accustomed to.
An example came in early August, when daily prices on the Dutch TTF gas exchange jumped from around €30/MWh to €40/MWh because of the threat of strikes among workers at Australian LNG production facilities. The market expected a possible strike to affect LNG availability as far afield as Europe.
Despite a more volatile market than in the past, the outlook for gas prices and availability in Europe and Finland this coming winter is stable. Underground storage levels are high, and several new LNG import terminals have been completed in Europe. Replacing Russian gas with LNG has been very successful both in Europe and in the Finnish–Baltic market.
Updated 16 May 2023
Gas prices on European exchanges have continued to fall since our previous update. The realised TTF gas exchange price was around €44/MWh for April and €42/MWh for May. At the time of writing, the forecast June price is around €35/MWh.
Gas prices have continued to fall for several reasons. A relatively warm winter and some gas users switching to oil and propane reduced gas demand during winter.
European gas storage levels also remain high for the season, and the market believes that replenishing them for next winter will be straightforward.
At the time of writing, the forecast TTF price for the coming autumn is around €50/MWh. The forecast for 2024 fluctuates slightly either side of €50/MWh.
Updated 1 March 2023
European gas exchange prices continued to fall throughout February. Reasons for the decline still include exceptionally warm weather and high European gas storage levels.
Daily TTF Front Month quotations for March recorded during February ranged between €47 and €60/MWh.
The current March Front Month index forecast is around €53/MWh (28 February).
Prices for the rest of the year are around €50/MWh
Summer prices are currently forecast at around €48/MWh. Prices for the rest of the year and next winter are also expected to remain significantly lower than last year, at approximately €45–57/MWh.
This is still significantly higher than the historical average of around €20/MWh, but the market clearly expects a more stable year than last year.
Confidence in lower prices than last year is supported by Europe’s still relatively full gas storage after a warm winter. Storage is currently around 60% full, compared with an average of around 40% at this time of year. The market believes that replenishing storage for next winter will be relatively easy. This is supported by Germany’s three new floating LNG receiving terminals, which feed gas brought by LNG ships into the network in the same way as the floating LNG import terminal commissioned in Inkoo, Finland.
One factor that could theoretically raise prices this year would be a significant rise in Chinese LNG demand following the lifting of COVID restrictions. A large share of LNG supplied from the United States, for example, has come to Europe while Chinese demand has been low because of lockdowns.
On the other hand, gas prices are currently very close to oil prices. Some large gas consumers temporarily switched to oil because of last year’s record gas prices. Some have already switched back to gas or are considering doing so, increasing gas demand and potentially slowing the fall in gas prices.
Updated 19 January 2023
European gas exchange prices fell significantly during December and January. Reasons include an exceptionally warm autumn and winter, apart from a cold spell lasting just over a week in early December, and high European gas storage levels.
Daily TTF Front Month prices fell from €140 to around €70 in December. Daily Front Month prices recorded in January have ranged from €70 down to around €55.
The current exchange price forecast for February is around €66/MWh (18 January). Summer forward prices are approximately €60/MWh.
A terminal vessel secures Finland’s gas supply
The LNG terminal vessel Exemplar arrived in Finland in December and is moored at the port of Inkoo and connected to the gas transmission network. Gas can now be supplied through the vessel to Finland and the Baltic countries.
The terminal vessel increased the capacity for supplying gas to Finland’s system from around 60 GWh to over 150 GWh per day.
A gas transmission pipeline explosion occurred in Latvia last weekend. Current information indicates that it was an accident. The explosion has had no impact on gas deliveries to Finland.
Europe’s gas price cap is €180/MWh
EU energy ministers reached agreement on a gas price cap in December. In the current market situation, activation of the cap looks highly unlikely.
In practice, the cap is activated if the TTF gas price exceeds €180/MWh for more than three consecutive days and is also €35/MWh above a reference basket comprising LNG price levels for deliveries to Europe, north-east Asia and the UK.
The price-cap mechanism takes effect on 15 February. It applies to all gas exchanges in Europe. Its application may be suspended if, while active, gas demand rises by more than 15% in one month and 10% in two months, if LNG imports into Europe fall significantly, or if TTF gas exchange trading volumes decline substantially.
Updated 28 October 2022
European gas exchange prices have continued to fall over the past two weeks. The main reasons are the same as at the previous update: warm weather in continental Europe, lower gas demand and very full European storage facilities.
This week (26 October), the forecast November TTF Front Month gas price is around €140/MWh, and December forward prices are around €133/MWh.
Forward quotations indicate prices of around €130–140 throughout next year, falling to approximately €94 in 2024.
Updated 12 October 2022
European gas exchange prices have fallen significantly in recent weeks from the late-August peak of over €300/MWh. Forecast prices for the rest of the year were still above €200/MWh in late September, but have fallen to around €160–170/MWh within two weeks.
The main reasons for the decline are Europe’s high underground gas storage level of around 90% and reduced gas use in industry, the public sector and households. The drought-related spike in electricity prices that pushed gas prices up in late August has also eased.
Leaks were detected in the Nord Stream pipelines in late September
Major leaks were detected in the Nord Stream I and II gas pipelines from Russia to Europe in late September. They were located in the Swedish and Danish exclusive economic zones near the island of Bornholm. Investigations have shown that the leaks were caused by explosions.
The Hamina terminal is ready, and an LNG terminal vessel is on its way to Inkoo
Finland’s security of gas supply has taken two significant steps forward.
The Hamina LNG terminal and storage tank have been completed and have already received their first LNG cargoes. The large LNG receiving terminal vessel leased by Gasgrid Finland is also on its way from South America to Finland. The terminal vessel’s market terms are expected to be submitted for a public consultation organised by the Energy Authority in the coming days.
Early this week (10 October), it was confirmed that the terminal vessel would be located on the Finnish side, at the port of Inkoo, for its first winter. The storage vessel is expected to arrive in Inkoo with an LNG cargo in late December.
The LNG terminal vessel provides temporary storage for imported LNG as it is regasified and fed into the gas transmission network. Its maximum regasification capacity is 140 GWh per day. Annual receiving capacity is up to 35 TWh. Finland’s total natural gas consumption in recent years has been around 25 TWh.
Updated 12 September 2022
European gas exchange prices have fluctuated in recent weeks, exceeding €300/MWh on several days. However, gas prices fell last week.
Forward prices for the rest of the year fell from around €250/MWh to €210–220/MWh. The main reasons were high continental European storage levels of 83%, reduced industrial gas consumption and a forecast of warm weather for the season. TTF gas prices are expected to decline gradually to around €180/MWh next year and approximately €125/MWh in 2024.
Following Nord Stream I’s annual maintenance, which ended in late July, Gazprom cut gas deliveries to Europe through the pipeline to just 20% of capacity. In late August, Gazprom stopped deliveries through Nord Stream I for three days of maintenance. Deliveries did not resume after those three days, and no gas is now reaching Europe via Nord Stream. Russia has cited technical difficulties, but the EU regards its actions as pressure on Europe related to the war in Ukraine. Russian gas is still reaching Europe via Ukraine and Turkey.
The European Commission and energy ministers have discussed the need for a cap on gas prices and currently record-high electricity prices in recent weeks. No decision has yet been made, but one is expected soon. The EU aims to reduce current energy prices ahead of the coming winter.
Updated 4 August 2022
European gas exchange prices rose significantly in late July when Russian President Putin announced that Gazprom would further restrict gas flows to Europe through Nord Stream I. Citing technical reasons, Russia cut deliveries through Nord Stream I from 40% to 20% of the pipeline’s capacity. Gas flows through Ukraine have remained unchanged.
At the beginning of August (3 August), gas exchange forward prices for September and the rest of the year are around €200/MWh. The latest price rise is almost entirely due to Russia’s cuts in NS1 pipeline deliveries and market concerns, particularly in Germany, about further reductions in Russian supplies.
European gas storage levels are already very high for the season thanks to substantial LNG imports. However, replenishment will become more difficult if Russian gas deliveries to Europe fall further.
Updated 21 July 2022
Scheduled annual maintenance on the Nord Stream I pipeline began on 11 July and ended today. No gas flowed to Europe through the pipeline during maintenance, but today flows towards Germany resumed at the same volume as before the shutdown. European gas exchange prices moved slightly lower at the same time. However, uncertainty remains about how much gas Russia will supply in future. Current flows are around 40% of Nord Stream I’s capacity.
We would again like to emphasise that Finland is receiving—and also received throughout Nord Stream I’s maintenance—normal gas supplies covering the country’s entire consumption via the Baltic countries and Balticconnector. In other words, the Nord Stream situation affected Finland’s gas market only through price fluctuations. Next winter, the floating LNG terminal leased by transmission system operator Gasgrid Finland will further improve security of supply.
SK index-based prices will be considerably lower in August than prices linked directly to TTF
Yesterday’s forecast August Front Month index price on the Dutch TTF gas exchange was around €165/MWh (20 July). However, customers using our SK index will pay considerably less in August. The SK index-based August gas price is around €120/MWh excluding VAT.
TTF gas prices of around €160/MWh are forecast for the rest of the year. There is currently considerable market uncertainty, including over how much gas Russia will send to Europe via Nord Stream in future.
Finland has already achieved the Commission’s proposed gas consumption reduction
The European Commission has proposed that Member States reduce gas consumption by 15% compared with normal years starting now, giving Europe a better chance to replenish gas storage before winter.
Finland’s gas consumption has already fallen by well over a quarter this year, considerably more than the Commission’s target. According to our current understanding, Finland therefore does not need to reduce consumption further to meet it.
Updated 28 June 2022
A great deal has happened in gas markets over the past two weeks. European gas exchange prices began rising when Russia reduced gas exports through Nord Stream I to Germany. A fire at one of the largest US LNG production plants has also raised European gas prices.
Following Monday 27 June 2022, the forecast July Front Month index price on the Dutch TTF exchange is around €105/MWh. Forward gas prices for the rest of the year are currently around €130/MWh.
European gas markets have shown uncertainty about next winter. Reduced Russian deliveries have slowed the replenishment of European gas storage. Germany, for example, has begun preparing for the possibility of Russian gas flows to Europe stopping. Plans are being drawn up to restrict industrial gas use and restart coal-fired power plants to secure supplies. At the same time, the EU is seeking as much LNG as possible from sources outside Russia.
Finland has sufficient gas, and a floating terminal will provide added security
Gas continues to arrive in Finland from the Baltic countries via Balticconnector in quantities covering the country’s entire demand. There is therefore no need to restrict consumption, even though Russian gas deliveries to Finland ended in late May.
Next winter, Finland’s security of supply will be strengthened by the floating LNG terminal leased by Gasgrid Finland. Its permanent location was recently confirmed as Fortum’s port in Inkoo. The terminal will allow LNG imports from around the world. The LNG will be regasified and fed into the gas network.
The LNG terminal is intended to be operational by next winter. It may spend its first winter on the Estonian side if the required port infrastructure is completed there before Finland. Its capacity is large enough that it should alone be able to cover all Finnish and Estonian gas demand. In addition, the Hamina LNG terminal aims to begin operating in October.
Updated 23 May 2022
Gas deliveries from Russia to Finland ended on Saturday 21 May 2022. This does not affect Suomen Kaasuenergia’s operations or gas deliveries. Even before the war in Ukraine, we imported almost all our gas from the Baltic countries.
Transmission system operator Gasgrid Finland Oy has also confirmed: all gas required by the Finnish market is now being imported from the Baltic countries via Balticconnector. In other words, Finland’s entire gas system is balanced and operating normally despite the closure of the Imatra entry point.
Finland’s transmission system operator has agreed to lease a terminal vessel
Gasgrid Finland announced on Friday that it had also signed a ten-year lease agreement with Excelerate Energy for a floating LNG terminal vessel. The vessel will improve Finland’s security of supply and help the entire Finnish market move away from Russian gas.
LNG arriving at the terminal vessel will be regasified on board and fed into the natural gas transmission network. The vessel’s storage and send-out capacity are sufficient to secure gas demand in both Finland and Estonia. The terminal vessel is intended to be operational by next winter.
Gas prices have been falling since last week
European gas exchange prices began falling last week. One reason is that European gas storage facilities are filling rapidly. If the current pace continues, storage will be nearly full by the end of September and should be sufficient even for a very cold winter.
The current forecast June gas price (TTF Front Month) is around €95/MWh. Today (23 May), however, the TTF exchange price briefly fell to around €83/MWh.
(This is a developing news article in which we have followed the impact of the war in Ukraine on gas markets since the war began. Previous updates and the original article appear below.)
Updated 18 May 2022
Several media outlets reported today that Russian natural gas deliveries to Finland could stop as early as this week. As we have stated before, Suomen Kaasuenergia believes it can supply all customers normally even if no gas arrives from Russia.
This is thanks to our diversified gas procurement, based mainly on gas transported to Finland via the Baltic countries. It includes LNG originating from countries such as the United States and Norway.
Updated 11 May 2022:
Gas deliveries to Finland and most of Europe continue normally from both the Baltic countries and Russia. European gas exchange prices are currently around €100/MWh. Yesterday (10 May), for example, the TTF gas hub’s forecast June price was approximately €98/MWh.
Almost all the gas Suomen Kaasuenergia sells to its customers comes from the Baltic countries. Gas reaches the Baltic countries as LNG from various sources around the world, but currently none comes from Russia.
The National Emergency Supply Agency’s early warning and Ukraine’s decision to halt Russian gas transit do not affect Suomen Kaasuenergia’s deliveries
Last week, the National Emergency Supply Agency issued an early warning to the European Commission about possible gas market disruptions in Finland. Declaring the early-warning level changes nothing for Suomen Kaasuenergia or our customers.
Germany, for example, has had such an early-warning level in place for weeks. The Agency’s announcement simply means that a gas supply disruption is possible. This is because Finland, like many other countries, has refused Russia’s demand to pay for gas in roubles.
There is currently no disruption to Russian gas deliveries in Finland of the kind described in the early warning. Even if one occurs later, we do not believe it will affect Suomen Kaasuenergia’s deliveries to customers. Almost all the gas we procure comes from the Baltic countries. In other words, we believe we can supply all customers normally even if no gas arrives from Russia.
Reports yesterday and today also stated that Ukraine had halted natural gas transit through a pipeline carrying gas from Russia to Europe via Ukraine. This news raised European gas exchange prices somewhat yesterday, but so far has no effect on Suomen Kaasuenergia’s operations or Finland’s overall security of gas supply.
Updated 4 May 2022
Gas deliveries to Finland continue normally from both Russia and the Baltic countries. Even before the war in Ukraine, Suomen Kaasuenergia procured most of the gas it sold via the Baltic countries. This includes LNG originating from countries such as the United States and Norway.
In recent days, public discussion has focused on the possibility that Russia might stop selling gas to Finland. This gained momentum when Russia stopped selling gas to Poland’s PGNiG and Bulgaria’s Bulgargaz last week. Russia continues to supply other European gas companies and Finland normally. Significant volumes also reach Finland via Balticconnector from the Baltic countries.
Thanks to our diversified procurement, Suomen Kaasuenergia currently does not believe that an end to gas deliveries via Imatra would affect our deliveries to customers.
Gas prices remain exceptional
Gas exchange prices remain exceptionally high, although they have fallen from their peak a few weeks ago. Prices also continue to fluctuate considerably from day to day and week to week. Dutch TTF exchange prices are currently around €95–100/MWh. Forecasts for next month and the following month are also around €100/MWh.
EU energy ministers met at a crisis meeting on Monday (2 May). Ministers were largely in agreement that Russian oil imports would probably be banned. They also discussed the unacceptability of Russia’s demand to pay for gas through the proposed rouble-payment mechanism in its current form. We are monitoring the situation actively.
The GIPL gas transmission pipeline connecting Poland and Lithuania was commissioned on 1 May. It physically connects Finland and the Baltic countries to the European gas market and should further improve security of supply. Finland and Estonia are also jointly exploring the lease of an LNG terminal vessel to further reduce the region’s dependence on Russian energy.
Updated 23 March 2022:
Gas deliveries to Finland and Europe continue normally, just as at the time of the previous update.
Gas prices during the war in Ukraine have been unprecedented, but exchange prices have fallen slightly this week and last week.
Yesterday (22 March 2022), the TTF gas exchange’s forecast April price was around €137/MWh. Despite the small decline, the exchange price remains historically exceptional: more than six times the long-term average of around €20/MWh.
Updated 8 March 2022:
The war between Russia and Ukraine has not affected gas deliveries: gas continues to flow normally to Europe, the Baltic countries and Finland. Finland receives gas via both the Imatra border point and the Balticconnector subsea pipeline as before, with no need to restrict gas consumption or deliveries. Gas reaches the Finnish and Baltic market from many sources, including LNG from the United States.
The war in Ukraine and the associated uncertainty have pushed gas exchange prices to unprecedented levels, even though prices were already historically exceptional. Yesterday (7 March 2022), the forecast April exchange price (TTF Front Month) was around €170/MWh. Daily fluctuations have also been unusual, reaching as much as €50/MWh in a day.
How the gas market operates during potential supply disruptions
Original article, 24 February 2022:
The conflict between Russia and Ukraine, which has escalated in recent weeks and culminated in an invasion this morning, has raised many questions about gas deliveries to Finland. To serve our customers as well as possible, we have compiled the information below on how the gas market operates during various disruptions and on gas price developments.
We monitor the gas market daily and update this article regularly, as there is currently considerable uncertainty. This morning’s attacks on Ukraine were immediately reflected in a movement in gas exchange prices.
We emphasise that gas is currently flowing to Finland entirely normally via both the Imatra border point and the Balticconnector subsea pipeline linking the Baltic countries and Finland. There is no need to restrict gas consumption or deliveries.
Finland receives gas from sources other than Russia
Some of the gas used in Finland still arrives directly from Russia through the Imatra border point. We do not currently believe that Imatra would be among the first entry points to close if Russia restricted gas exports to Europe. Any export restrictions would nevertheless certainly affect Finnish gas prices, which are linked to pricing on central European gas exchanges.
If gas flows through Imatra stopped, Finland could receive gas from the Baltic countries through Balticconnector beneath the Gulf of Finland. When temperatures are above zero degrees Celsius, Balticconnector’s capacity is sufficient to cover almost all of Finland’s current gas consumption.
Latvia also has a large underground gas storage facility with a capacity equivalent to Finland’s annual gas consumption. Lithuania has a commercially operated, open-access LNG import terminal through which significant volumes of LNG from around the world can enter the Finnish and Baltic market area.
All this means that significant quantities of gas already reach Finland from sources other than Russia. In exceptional circumstances involving disruptions to Russian supplies, efforts would be made to increase volumes from those other sources.
How the gas market operates during gas availability disruptions
In a major disruption affecting gas availability, transmission system operator Gasgrid Finland Oy would instruct gas suppliers to restrict deliveries if force majeure prevented them from procuring as much gas as their customers required.
Even in such circumstances, the starting point is to make every effort to maintain supplies to customers paying the compulsory stockholding fee: households, heating users and transport users.
Further information is available on the transmission system operator’s website: gas supply disruptions.
If gas use had to be severely restricted in exceptional circumstances, the National Emergency Supply Agency would authorise the use of compulsory stocks. Suomen Kaasuenergia would then follow the instructions of Gasgrid Finland and the authorities on matters including restrictions on gas deliveries and the use of operators’ own compulsory stocks.
However, we emphasise that we currently regard this situation as highly unlikely. More information is also available via the Gasgrid link above.
The crisis in Ukraine is keeping gas prices high
European gas exchange prices have been exceptionally high for several months, although they fell from their peak after the end of last year. Since early January, the TTF Front Month index, which indicates next month’s gas price, has remained between €70 and €95/MWh. The current forecast March exchange price is around €76–77/MWh (23 February). Daily price fluctuations remain substantial.
Many factors supporting high prices have eased as spring approaches. Thanks to a warm winter, European gas storage levels have moved closer to those of previous years, as less gas than usual has been consumed. More LNG deliveries have also reached Europe than towards the end of last year.
The crisis between Russia and Ukraine is currently the most significant factor maintaining high gas prices and considerable market uncertainty. This morning’s attacks on Ukraine immediately pushed gas exchange prices up somewhat.
The impact of high gas prices on gas bills
We are well aware that rising gas prices have significantly increased our customers’ bills. We have therefore offered customers the option of paying in instalments. Our customer service team will be happy to provide more information.
Gas used by consumers is also covered by social assistance, if paying in instalments does not help.
The SK index used to price several of our gas products has also provided customers with protection amid price fluctuations. SK index-based pricing is more stable than pricing linked directly to exchange prices, because we fix SK index prices during the three months preceding the gas delivery month. This smooths and delays the effect of price changes on gas bills, although it does not eliminate them entirely.